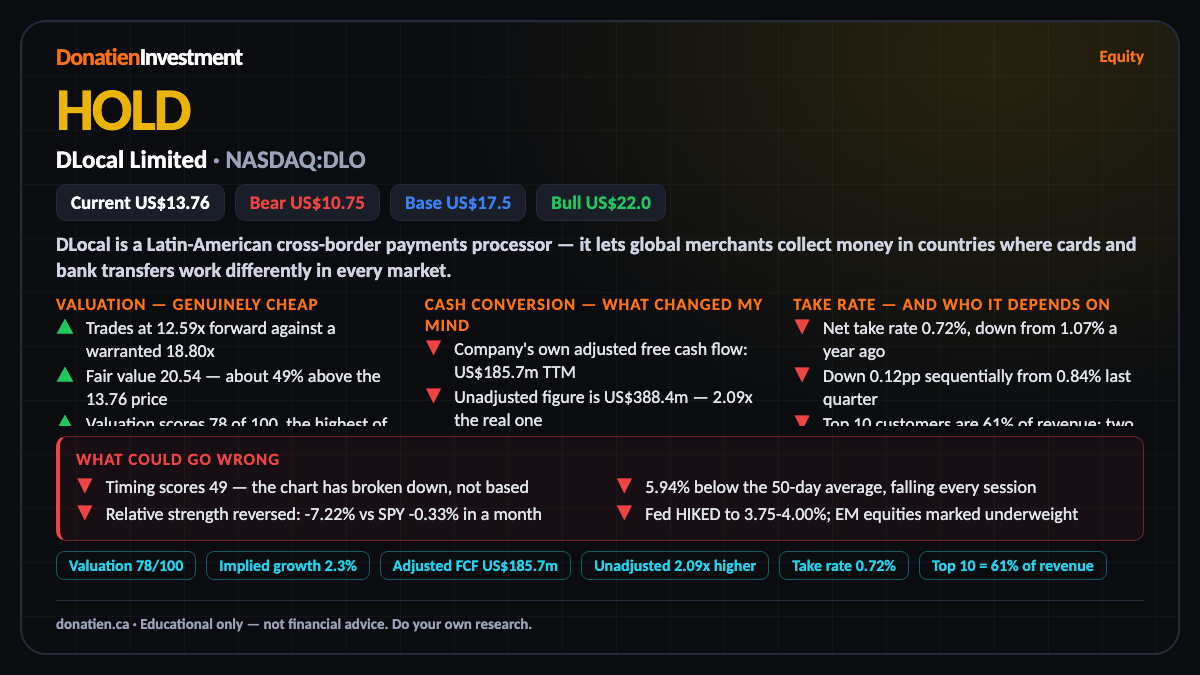
DLocal Limited (NASDAQ:DLO) HOLD
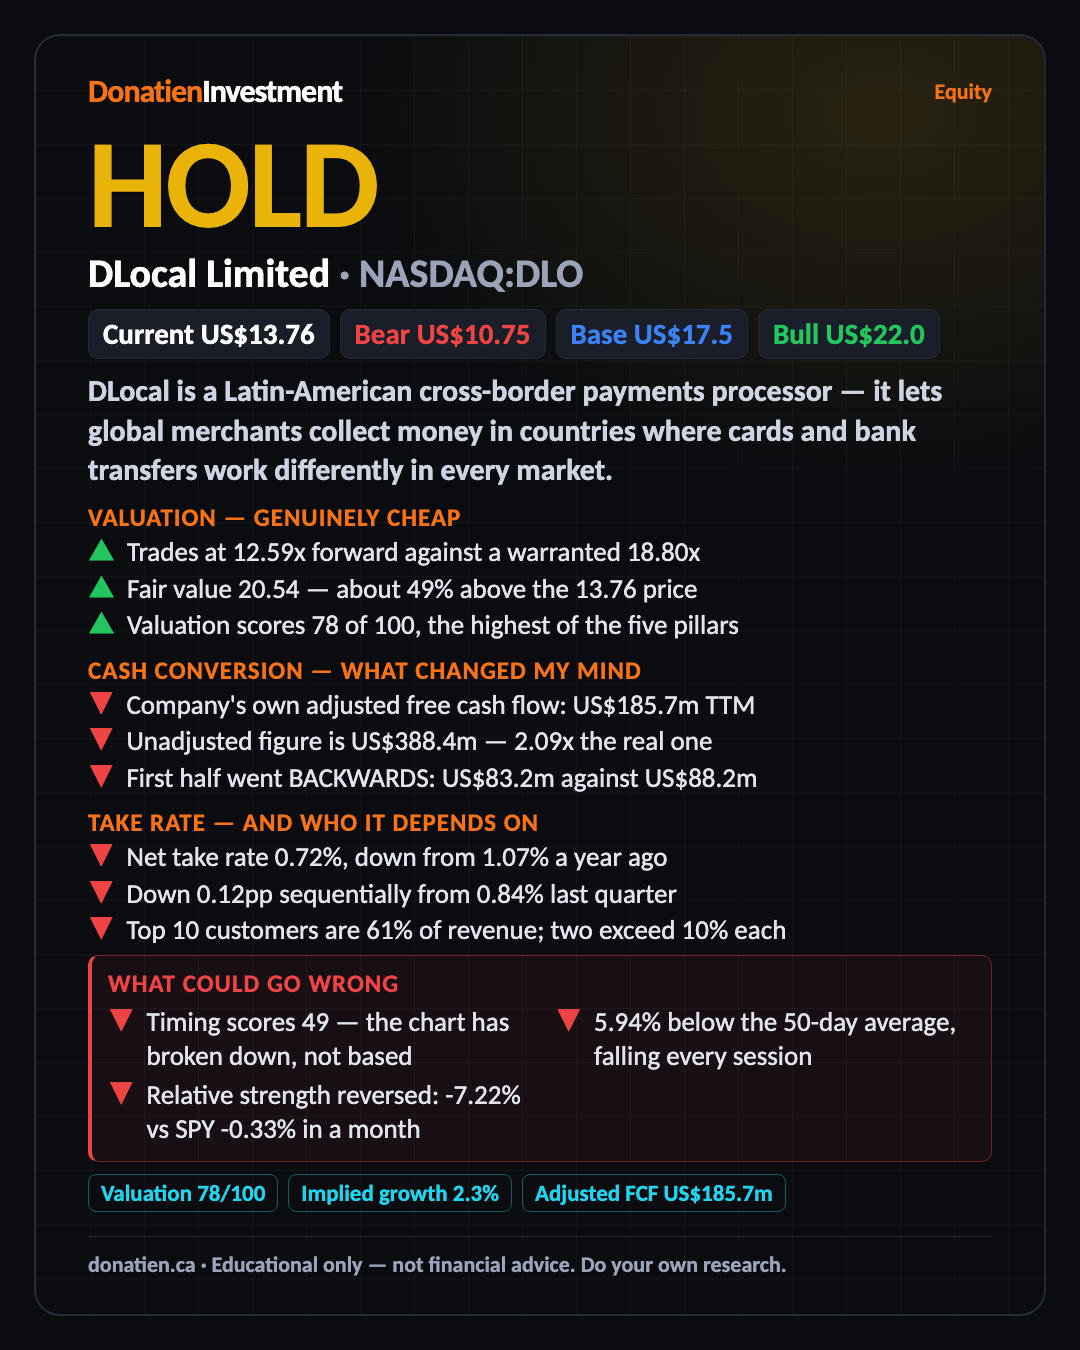
Cheap on the numbers and not yet corroborated by anything else. The price sits a third below what my model says the earnings justify, but the take rate is falling, the cash conversion is half what the screens report, and the chart has broken down. A cheap price is a reason to watch, not a reason to act.
dLocal is a Latin-American cross-border payments processor — it lets global merchants collect money in countries where cards and bank transfers work differently in every market. I had this at HOLD short-term and BUY on the medium and long horizons last month. All three are now HOLD, and the reason is not the price.
Valuation — genuinely cheap
The valuation is the real argument for owning this. I derive what the multiple ought to be from a two-stage model rather than borrowing a sector average, and it comes out at eighteen point eight times forward earnings. The shares change hands at twelve and a half times. That gap puts fair value around twenty dollars fifty against a price of thirteen seventy-six. Work backwards from the price instead, and the market is paying for about two and a third per cent of long-run growth from a company that grew revenue fifty-five per cent last quarter. Either the market is wrong, or it has seen something the multiple does not capture. The rest of this report is about that second possibility.
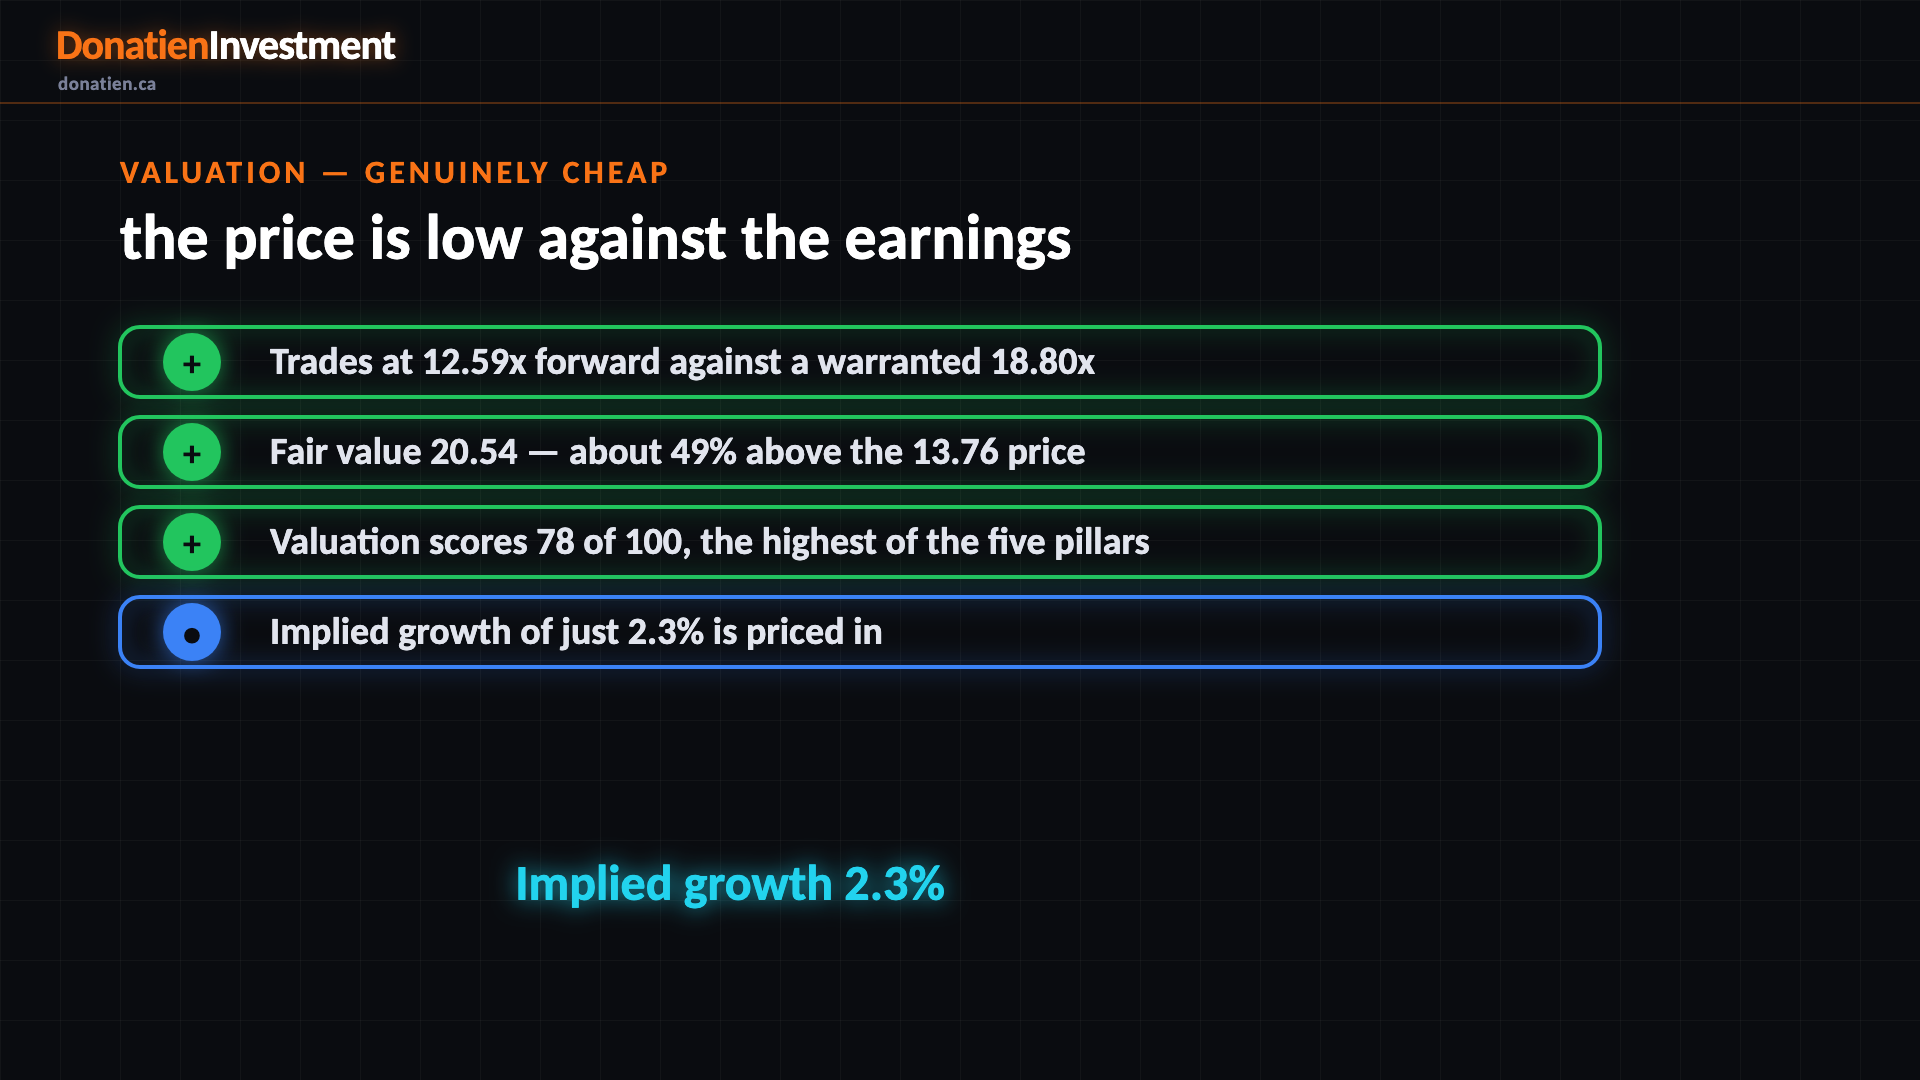
Valuation 78/100 · Implied growth 2.3%
Cash conversion — what changed my mind
A payments processor holds money that belongs to its merchants while it moves between countries. That float lands in operating cash flow and makes the cash generation look far better than it is. dLocal strips it out and publishes its own adjusted figure: a hundred and eighty-five point seven million over the trailing year, against three hundred and eighty-eight point four million unadjusted. The provider number is more than twice the company's own. What moved me was the half-year comparison — on the company's definition, cash generation fell five point six per cent while payment volume rose eighty-three per cent and revenue rose fifty-five. Growing that fast while converting less cash is the combination worth paying attention to.
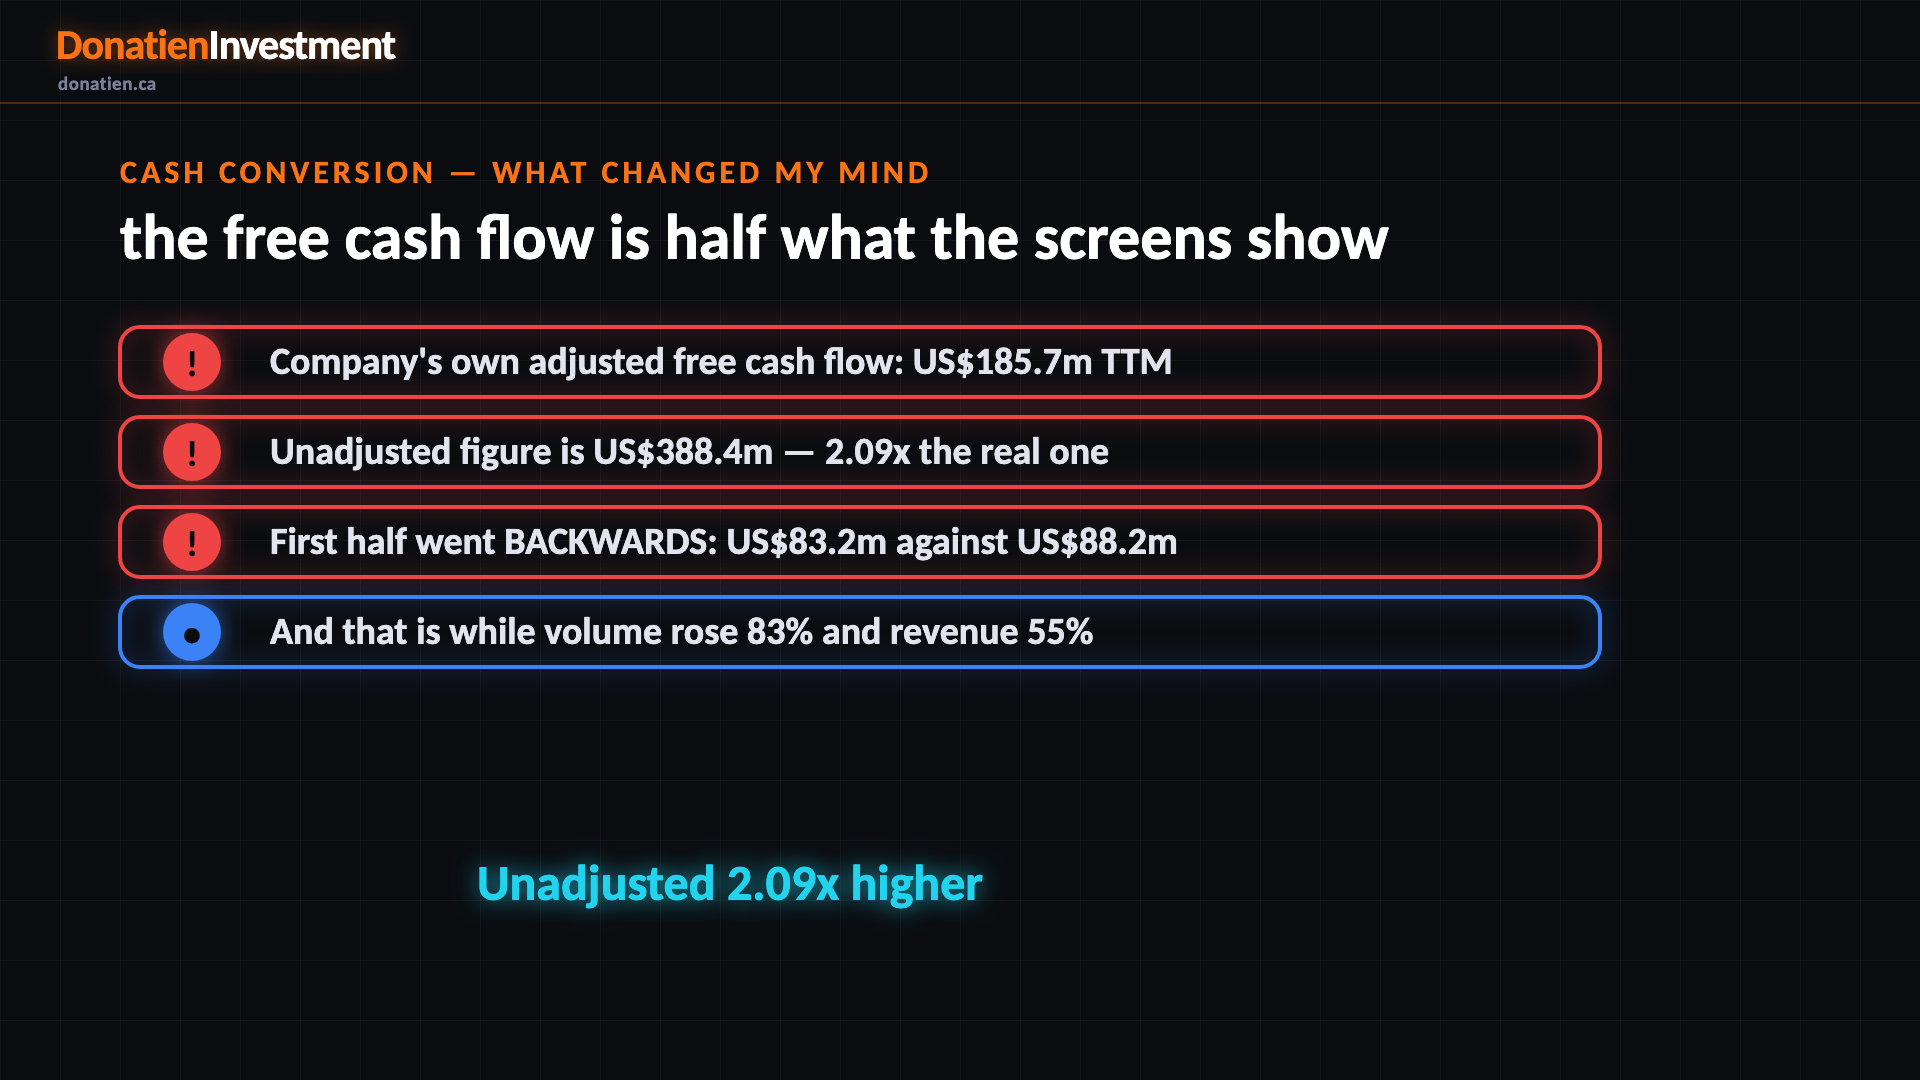
Adjusted FCF US$185.7m · Unadjusted 2.09x higher
Take rate — and who it depends on
The take rate is what dLocal keeps from every dollar that passes through it, and it has fallen from one point oh seven per cent a year ago to nought point seven two. Management attributes the latest step down to a single very large ride-hailing merchant crossing into a lower volume-pricing tier, and says that excluding that merchant the rate was roughly flat. I accept the mechanism — it is mix, not broad discounting. But the same fact makes the concentration worse rather than better: the top ten customers are sixty-one per cent of revenue and two of them individually exceed a tenth of it. A business whose pricing moves when one customer renegotiates is a business with less control over its own economics than the growth rate suggests.
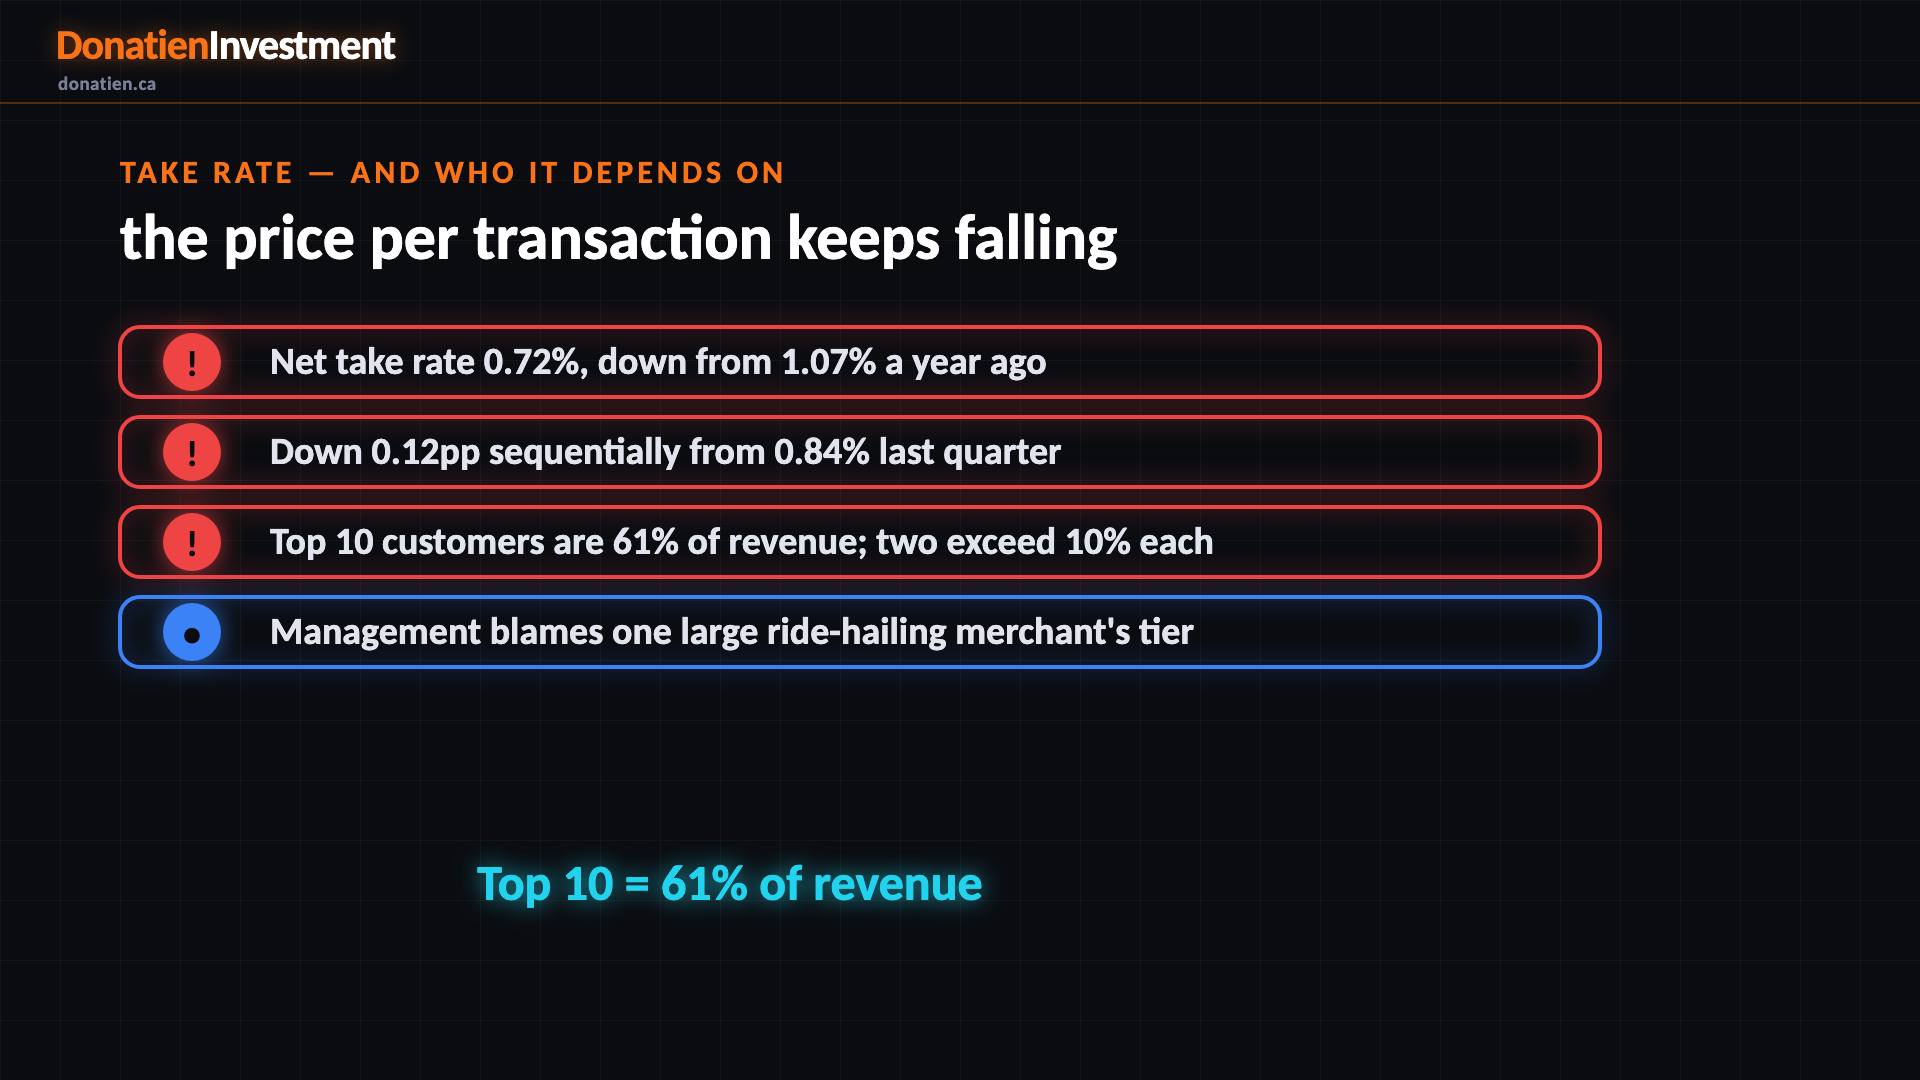
Take rate 0.72% · Top 10 = 61% of revenue
What could go wrong
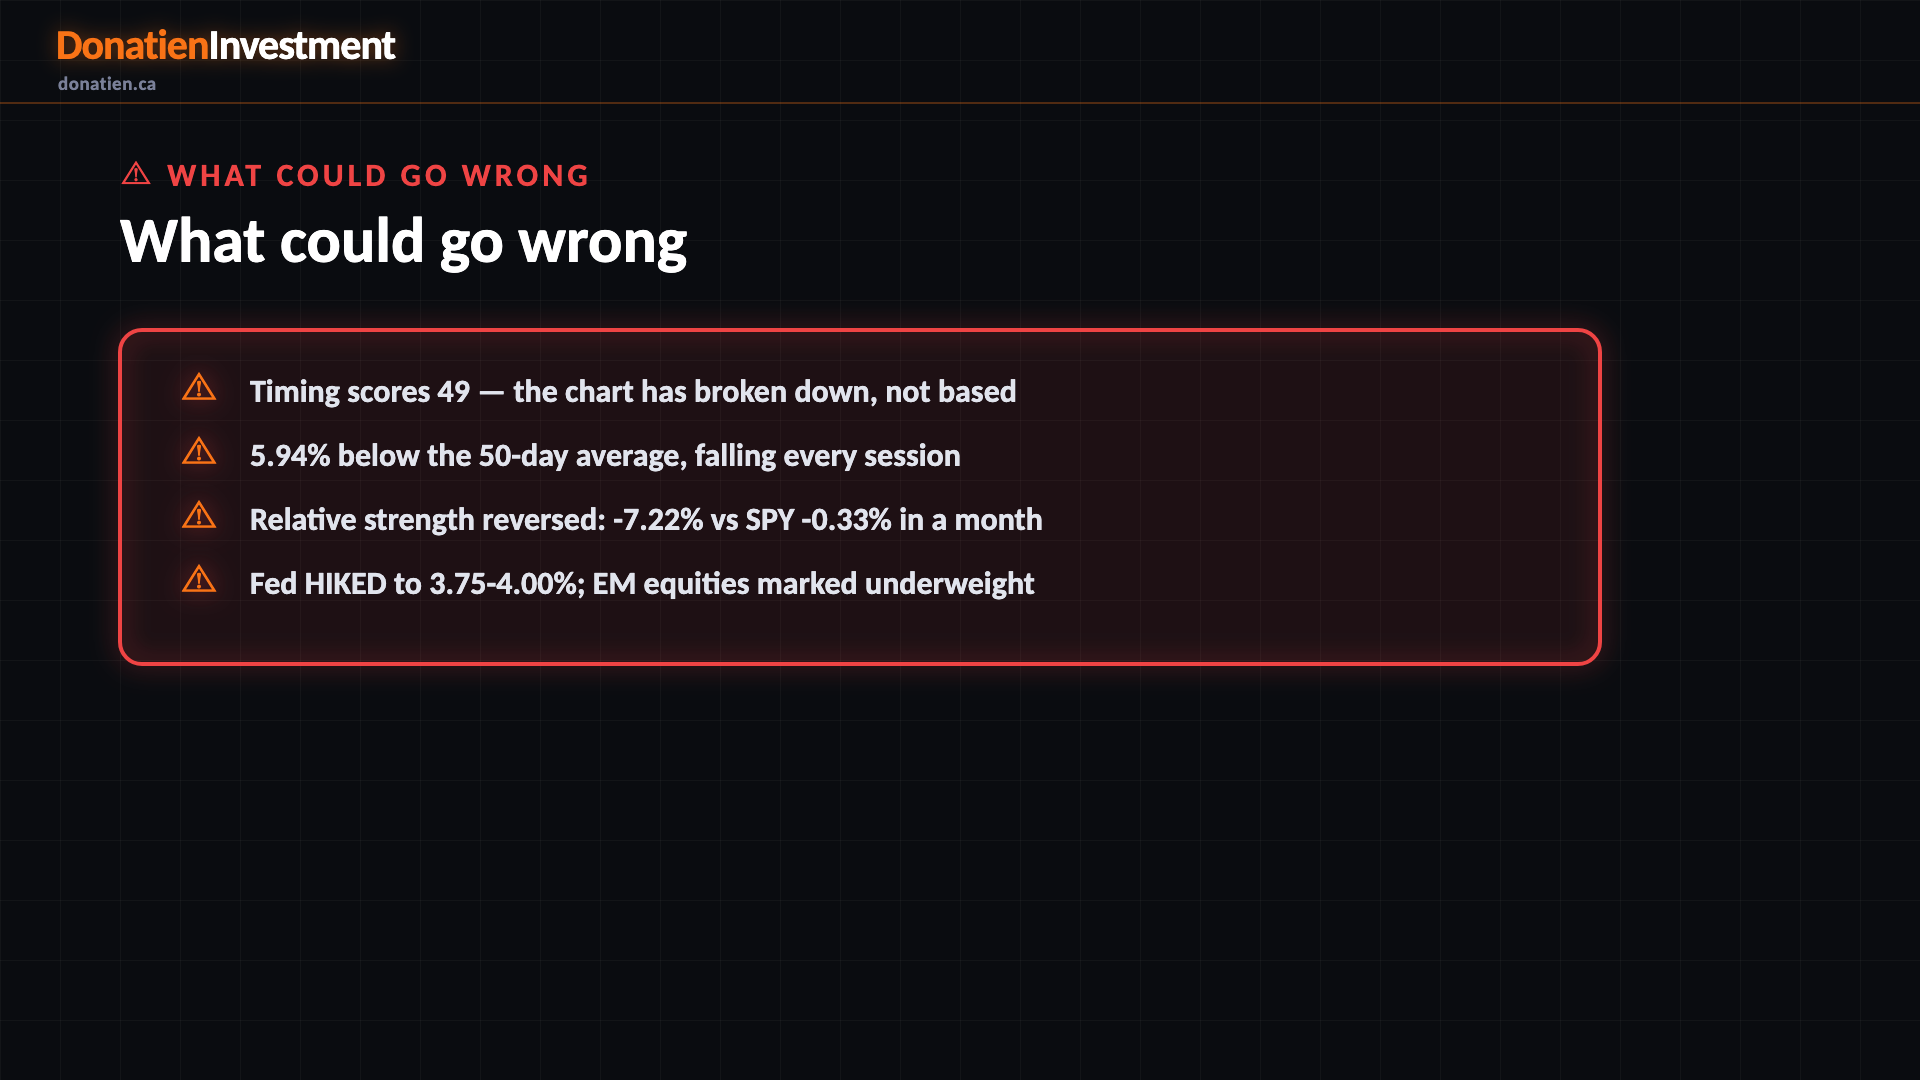
The risks are why this is a hold and not a purchase. The chart has broken down rather than bottomed: price sits almost six per cent below its fifty-day average, which has fallen every session for a fortnight, and the momentum indicator has been negative for sixteen consecutive sessions. Relative strength has reversed outright — down seven per cent over a month while the broad market was flat and technology rose. The macro backdrop is against it too: the Federal Reserve has raised rates to three three-quarters to four per cent, the ten-year sits at five point two six, and emerging-market equities are marked underweight across every horizon. On top of that, the company paid out one and three-quarter times its own free cash flow in buybacks and dividends in the first half. My bear case is ten seventy-five, which is a twenty-two per cent fall from today.
Risk vs Reward
Against the current US$13.76, the report frames a bull case at US$22.0 (+60%), a base case at US$17.5 (+27%) and a bear case at US$10.75 (-22%). See the full report for the probability weight behind each path.
Read the full report on donatien.ca →