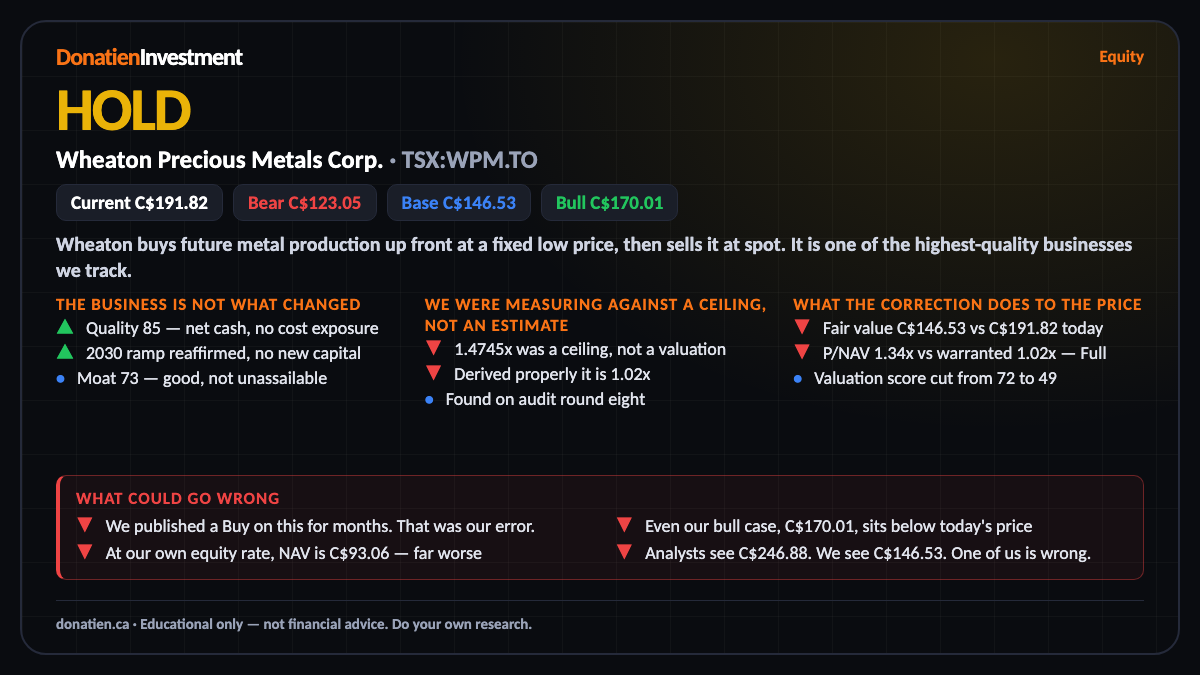
Wheaton Precious Metals Corp. (TSX:WPM.TO) HOLD
The business is excellent and the price already pays for it. We also got the valuation method wrong for months, and correcting it is what moved this from a Buy to a Hold.
Wheaton buys future metal production up front at a fixed low price, then sells it at spot. It is one of the highest-quality businesses we track. This update is not about the company — it is about a mistake in how we were valuing it.
The business is not what changed
Nothing in the business deteriorated. Wheaton still scores 85 on quality, which is near the top of anything we cover. It carries net cash rather than debt, at 0.67 times earnings before interest, tax, depreciation and amortisation. Because it buys metal at a fixed low price rather than digging it up, it has no exposure to mining cost inflation and no sustaining capital to fund. The 2030 production ramp was reaffirmed without new capital. If you own it for the business, the business is intact.
We were measuring against a ceiling, not an estimate
Our framework values a streamer on price to net asset value. It compares the multiple the market pays against a warranted multiple we are supposed to derive, capped by a sector ceiling. We had been publishing that ceiling as though it were the derived figure. The derivation had never been run at all. Net asset value is already a discounted cash flow, so one times is fair by construction, and any premium above it has to be argued for separately. Derived properly the warranted multiple is one point zero two.
What the correction does to the price
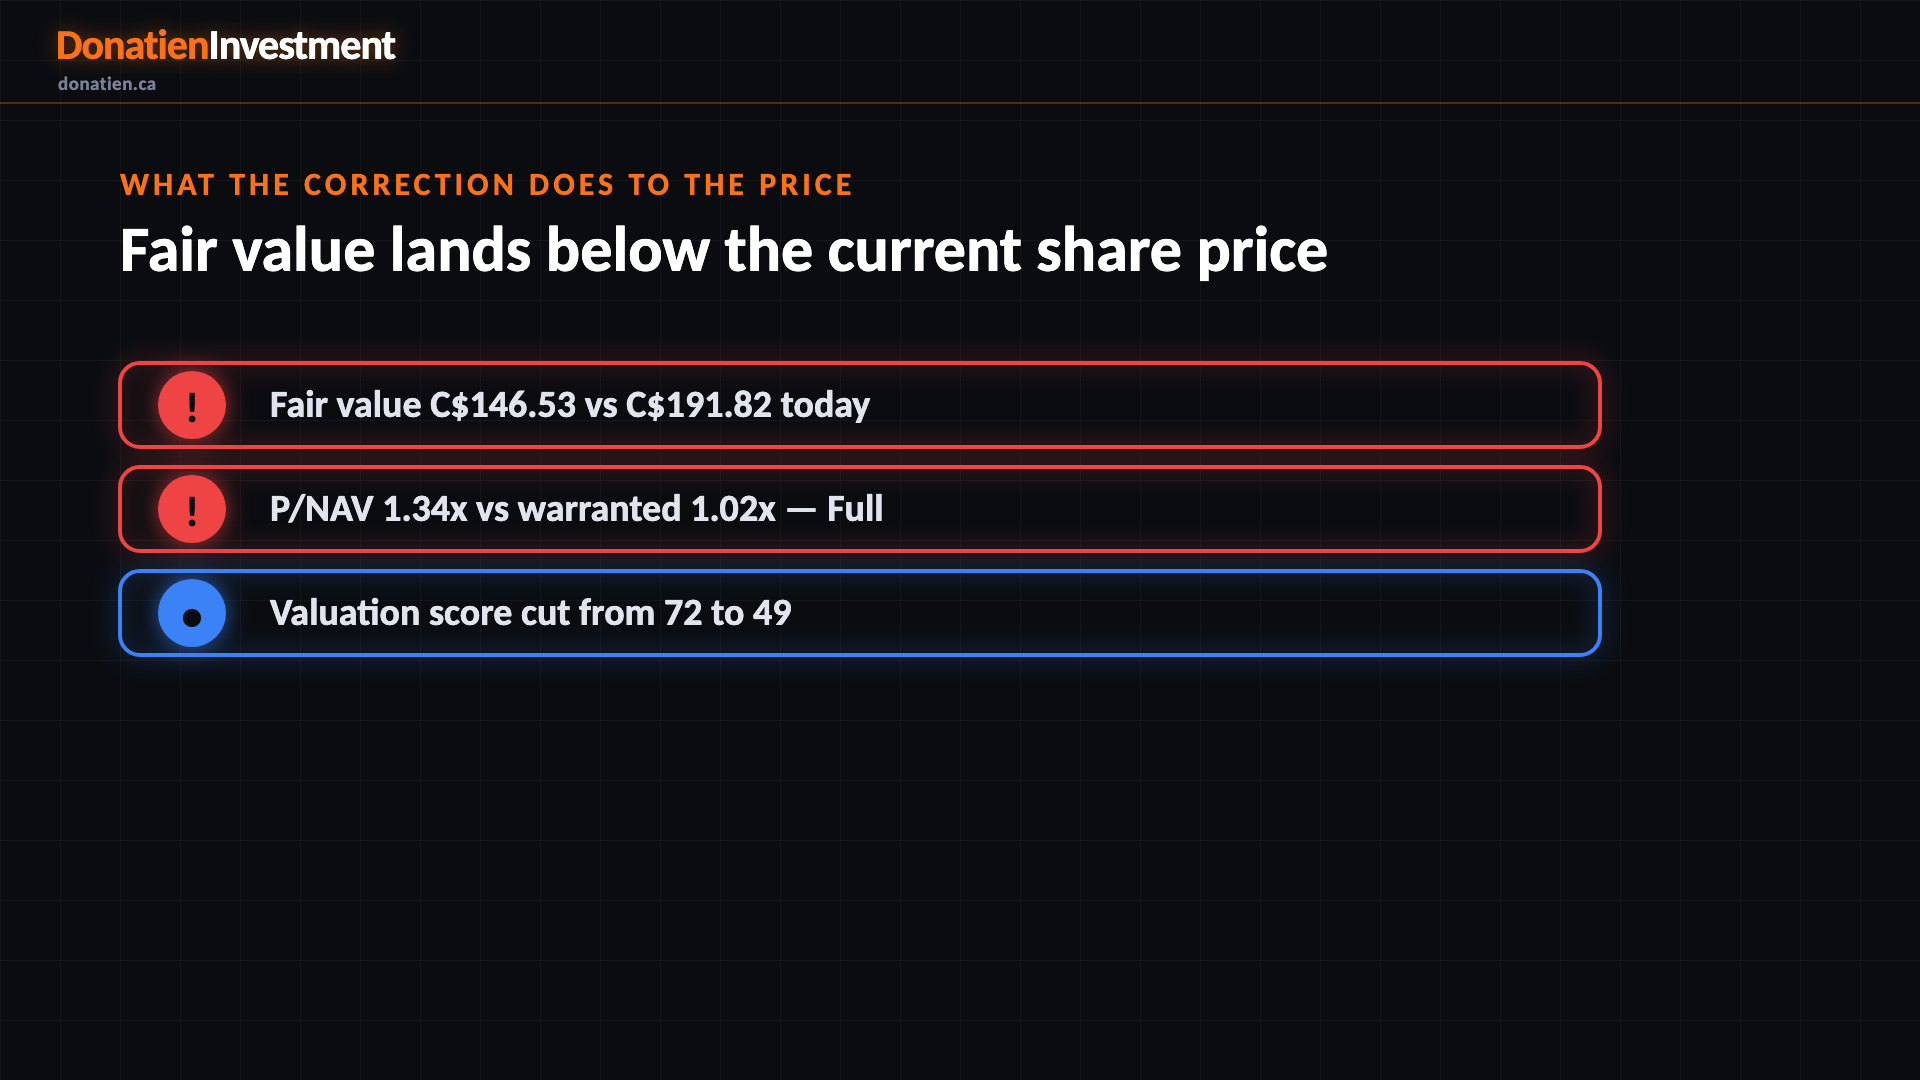
The premium we had been granting was already paid for somewhere else. We discount Wheaton's cash flows at five percent because they are contracted and low risk — and that low rate is itself the premium. Charging again for the same low risk on top of it counted it twice. Strip that out and fair value is one hundred and forty six dollars fifty three against a share price of one hundred and ninety one eighty two. The shares sit about thirty one percent above it. That is a hold, not a buy.
What could go wrong
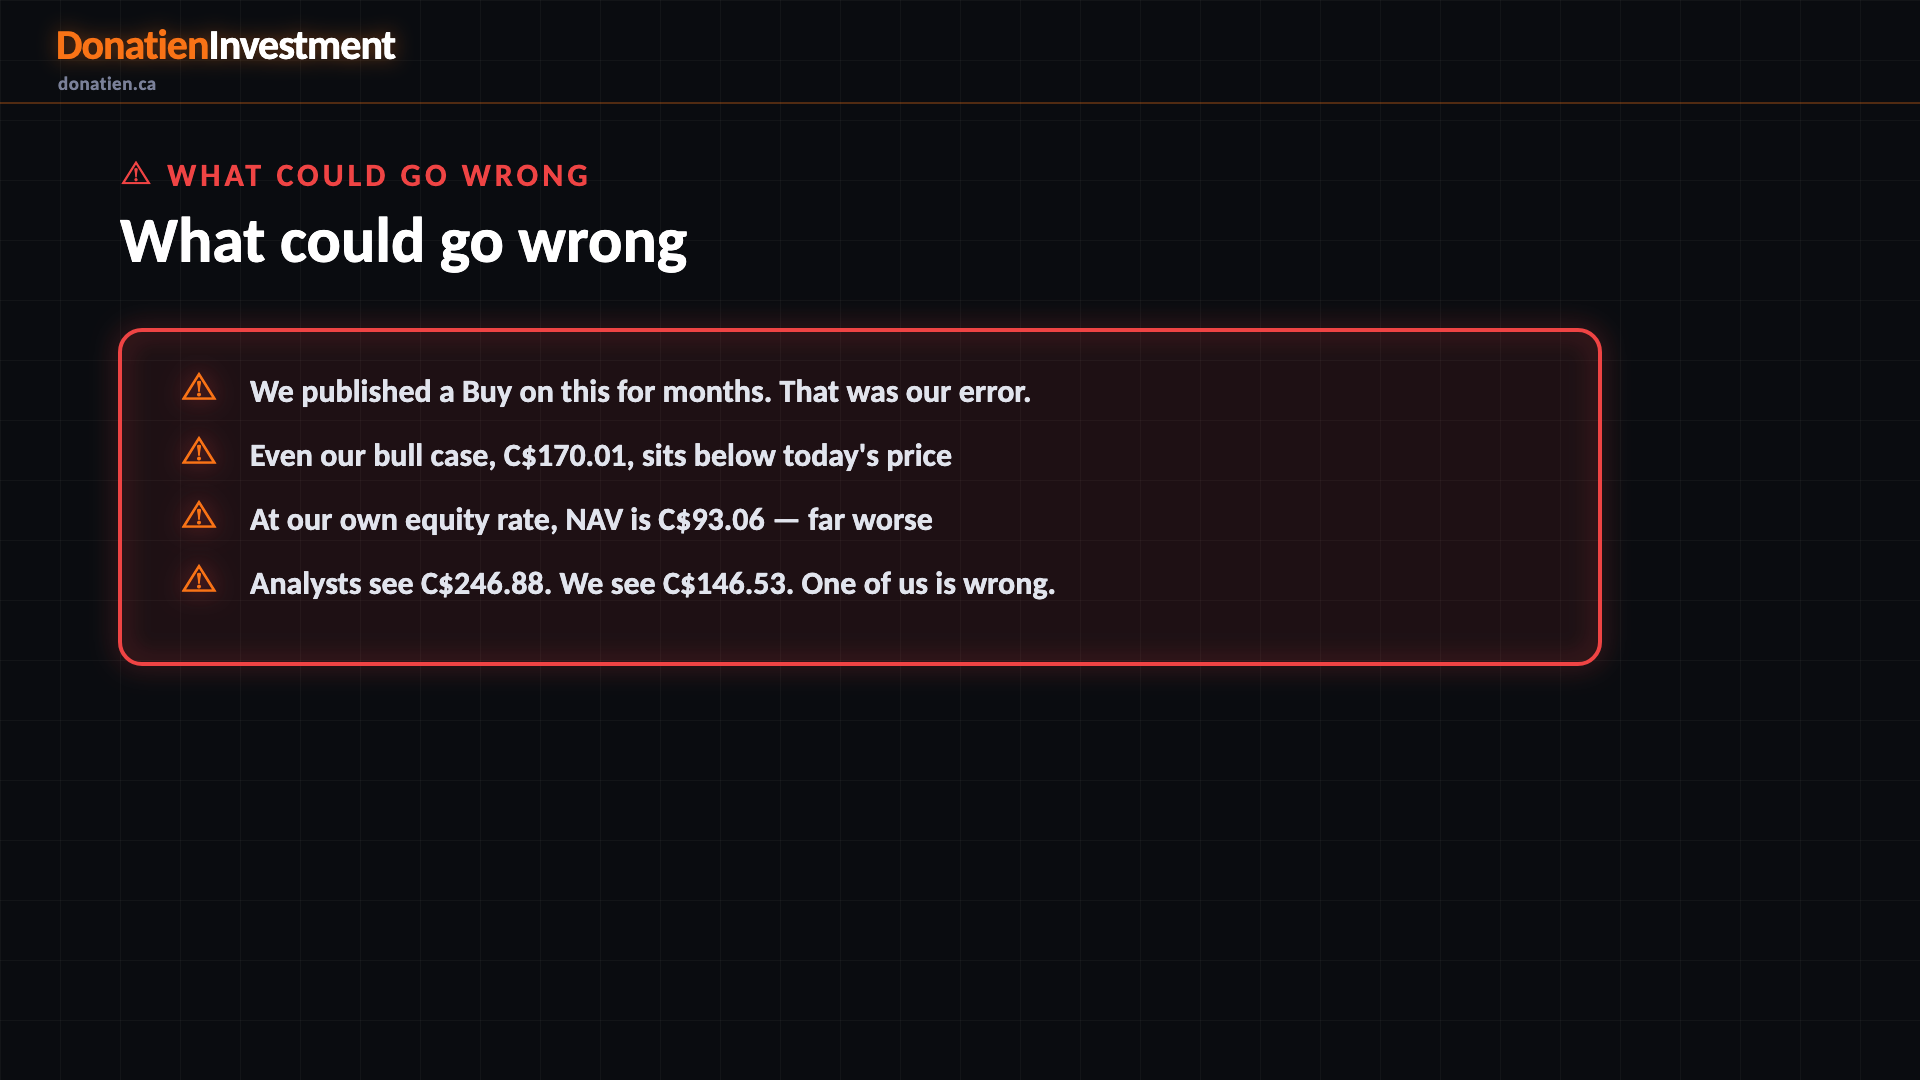
We published a Buy on this for months. That was our error. Even our bull case, C$170.01, sits below today's price. At our own equity rate, NAV is C$93.06 — far worse. Analysts see C$246.88. We see C$146.53. One of us is wrong.
Risk vs Reward
Against the current C$191.82, the report frames a bull case at C$170.01 (-11%), a base case at C$146.53 (-24%) and a bear case at C$123.05 (-36%). See the full report for the probability weight behind each path.
Read the full report on donatien.ca →