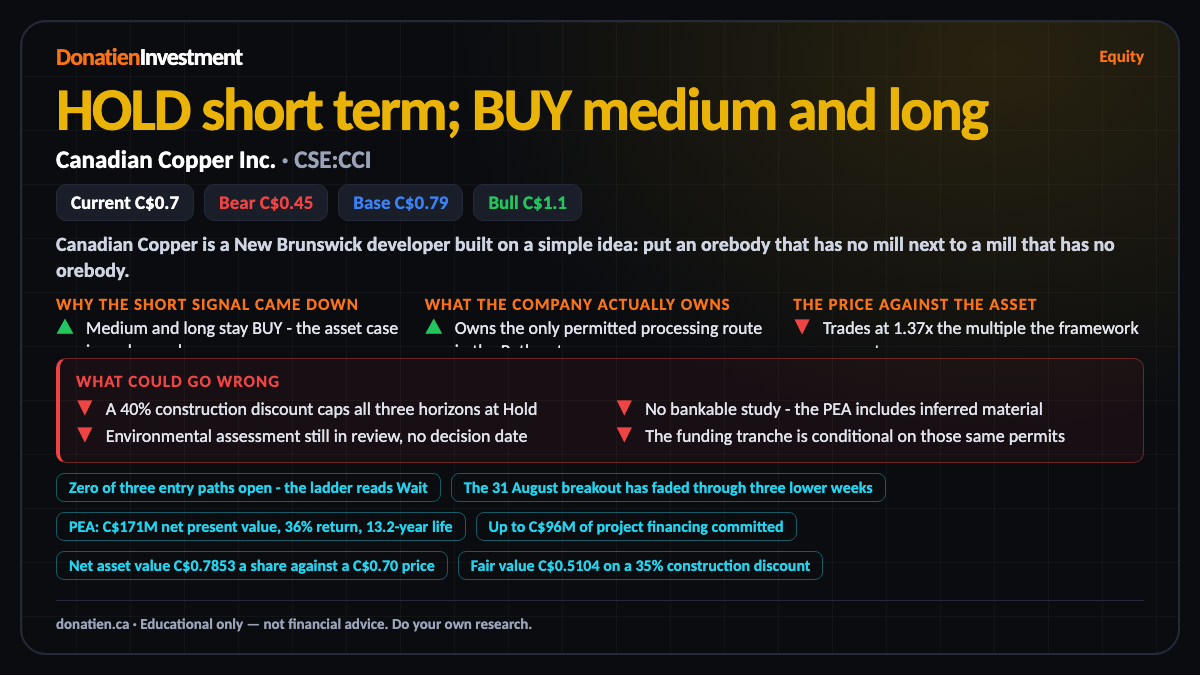
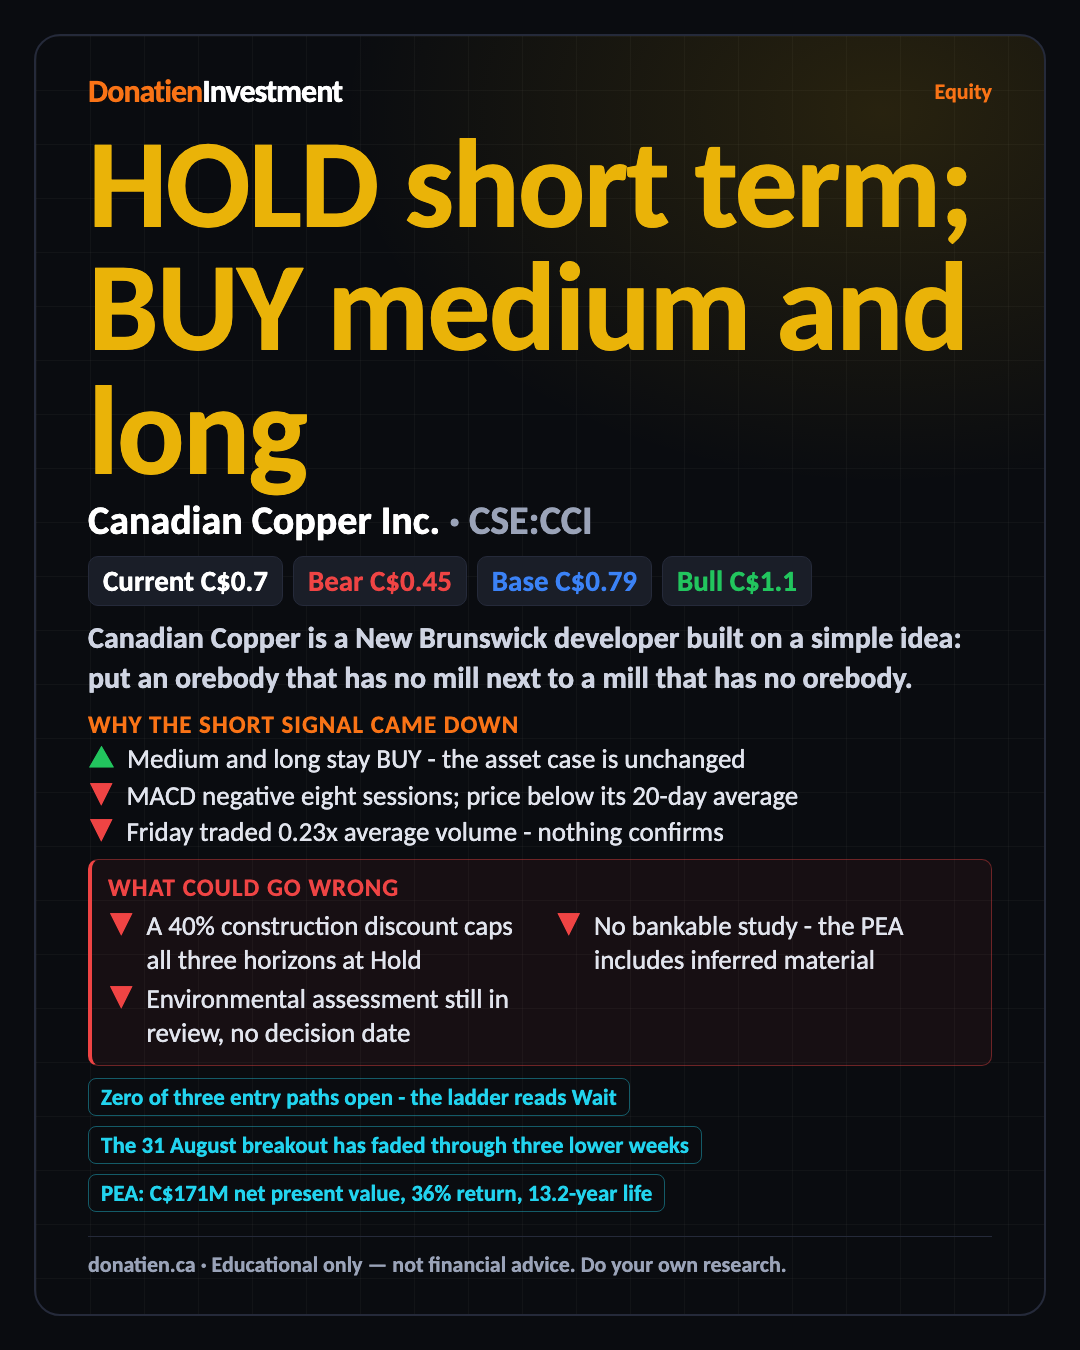
Canadian Copper Inc. (CSE:CCI) HOLD short term; BUY medium and long
Not one of the three entry paths is open, so the framework caps the short horizon at Hold. The asset case is intact and the medium and long horizons stay BUY.
Canadian Copper is a New Brunswick developer built on a simple idea: put an orebody that has no mill next to a mill that has no orebody. It owns the Murray Brook deposit and, since July, the Caribou processing plant thirteen kilometres away, already permitted and previously operated by Trevali. Despite the name, most of the revenue is zinc. It stays a Donatien Pick because there is a BUY on the medium and long horizons. What changed since the 11 September report is the tape, and what I got wrong in my own last report.
Why the short signal came down
The framework will not issue a short-term buy without a confirmed timing path, and there is not one here. The breakout at the end of August that justified the last report's short buy has faded through three consecutive lower weekly closes. The MACD histogram has been negative for eight straight sessions. Price sits below its twenty-day average, and Friday traded less than a quarter of normal volume, which confirms nothing in either direction. So the short horizon is capped at hold - buy on confirmation. Medium and long are untouched by that rule and both remain buy. This is a comment on the tape, not on the company.
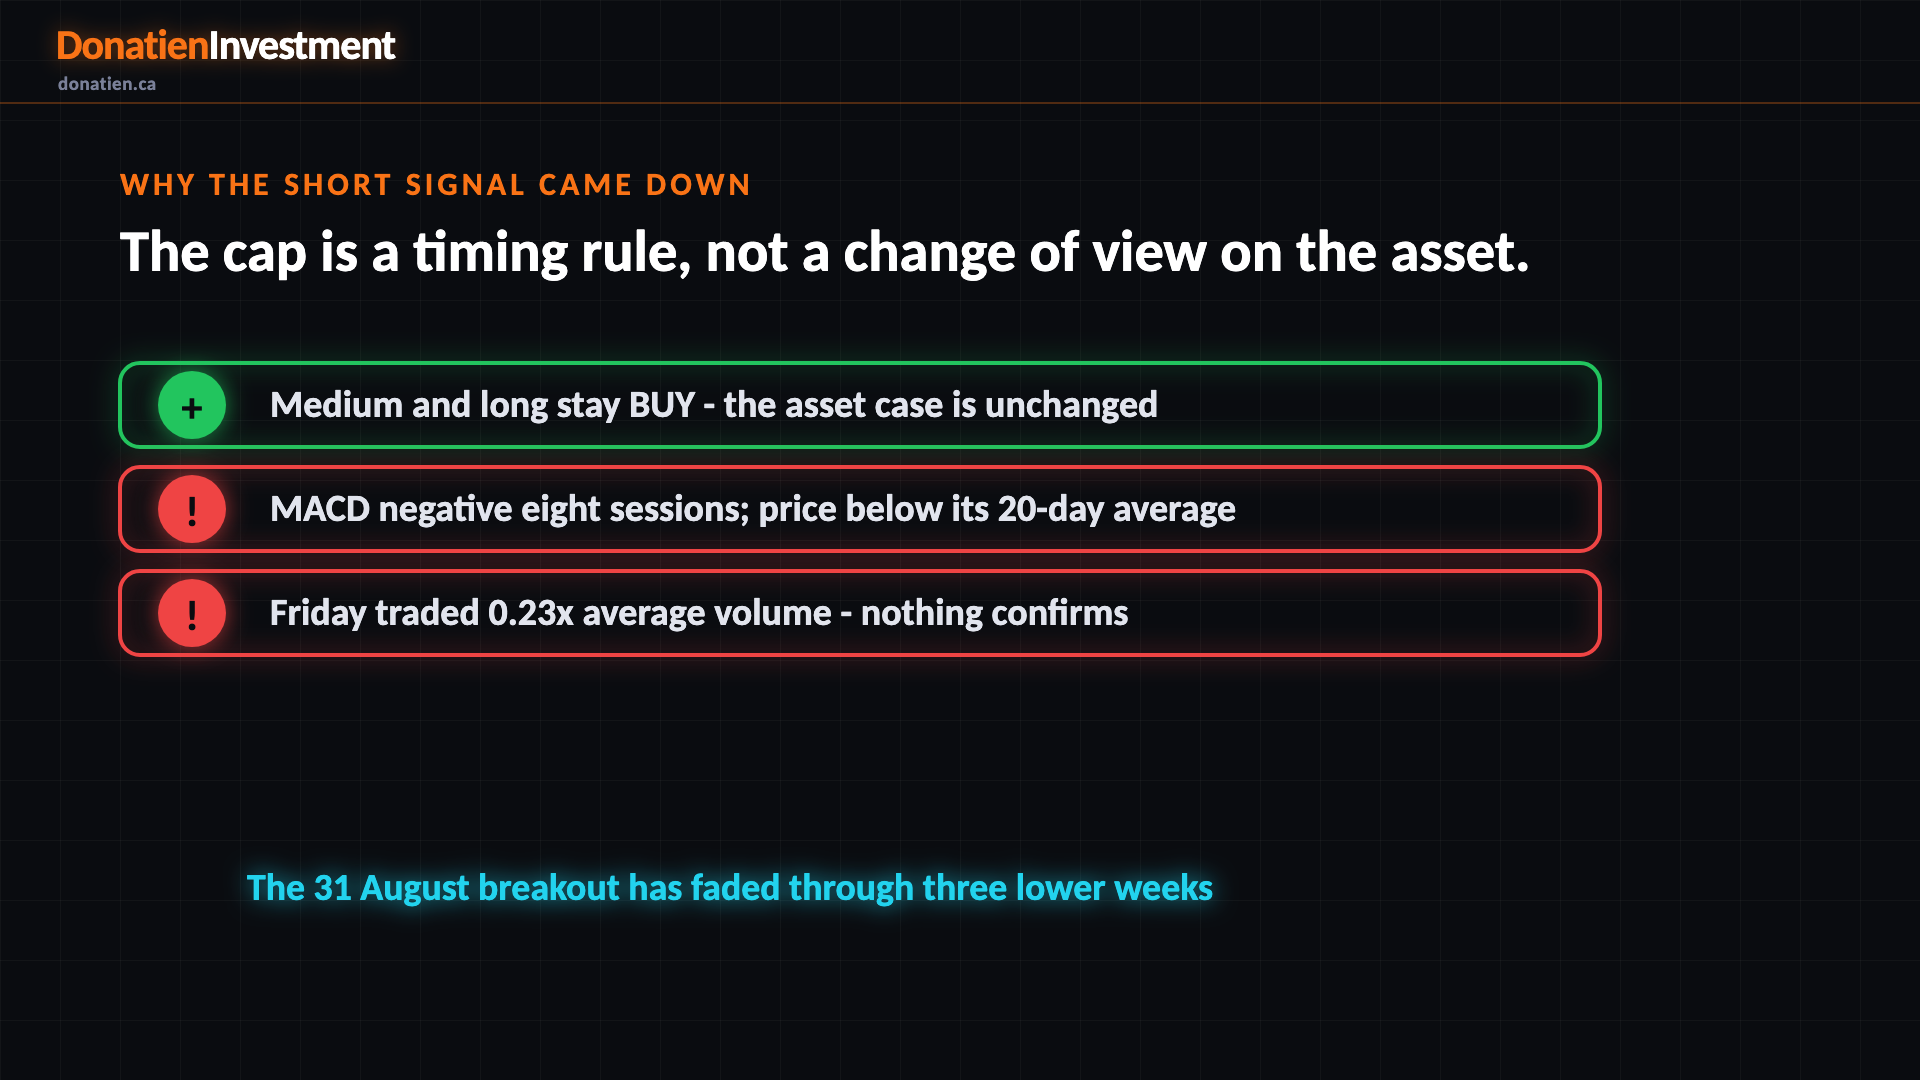
Zero of three entry paths open - the ladder reads Wait · The 31 August breakout has faded through three lower weeks
What the company actually owns
The study puts a one hundred and seventy-one million dollar after-tax net present value on the project, a thirty-six per cent internal rate of return and a thirteen point two year mine life, on sixty-four million dollars of initial capital. That capital cost is small because the plant already exists: a past-producing three thousand tonne a day mill with its own permits and a permitted tailings facility, thirteen kilometres from the pit, with title transferred in July. Replacing it would cost several hundred million and take years. Up to ninety-six million dollars of financing is committed against that capital cost, though most of it is conditional.
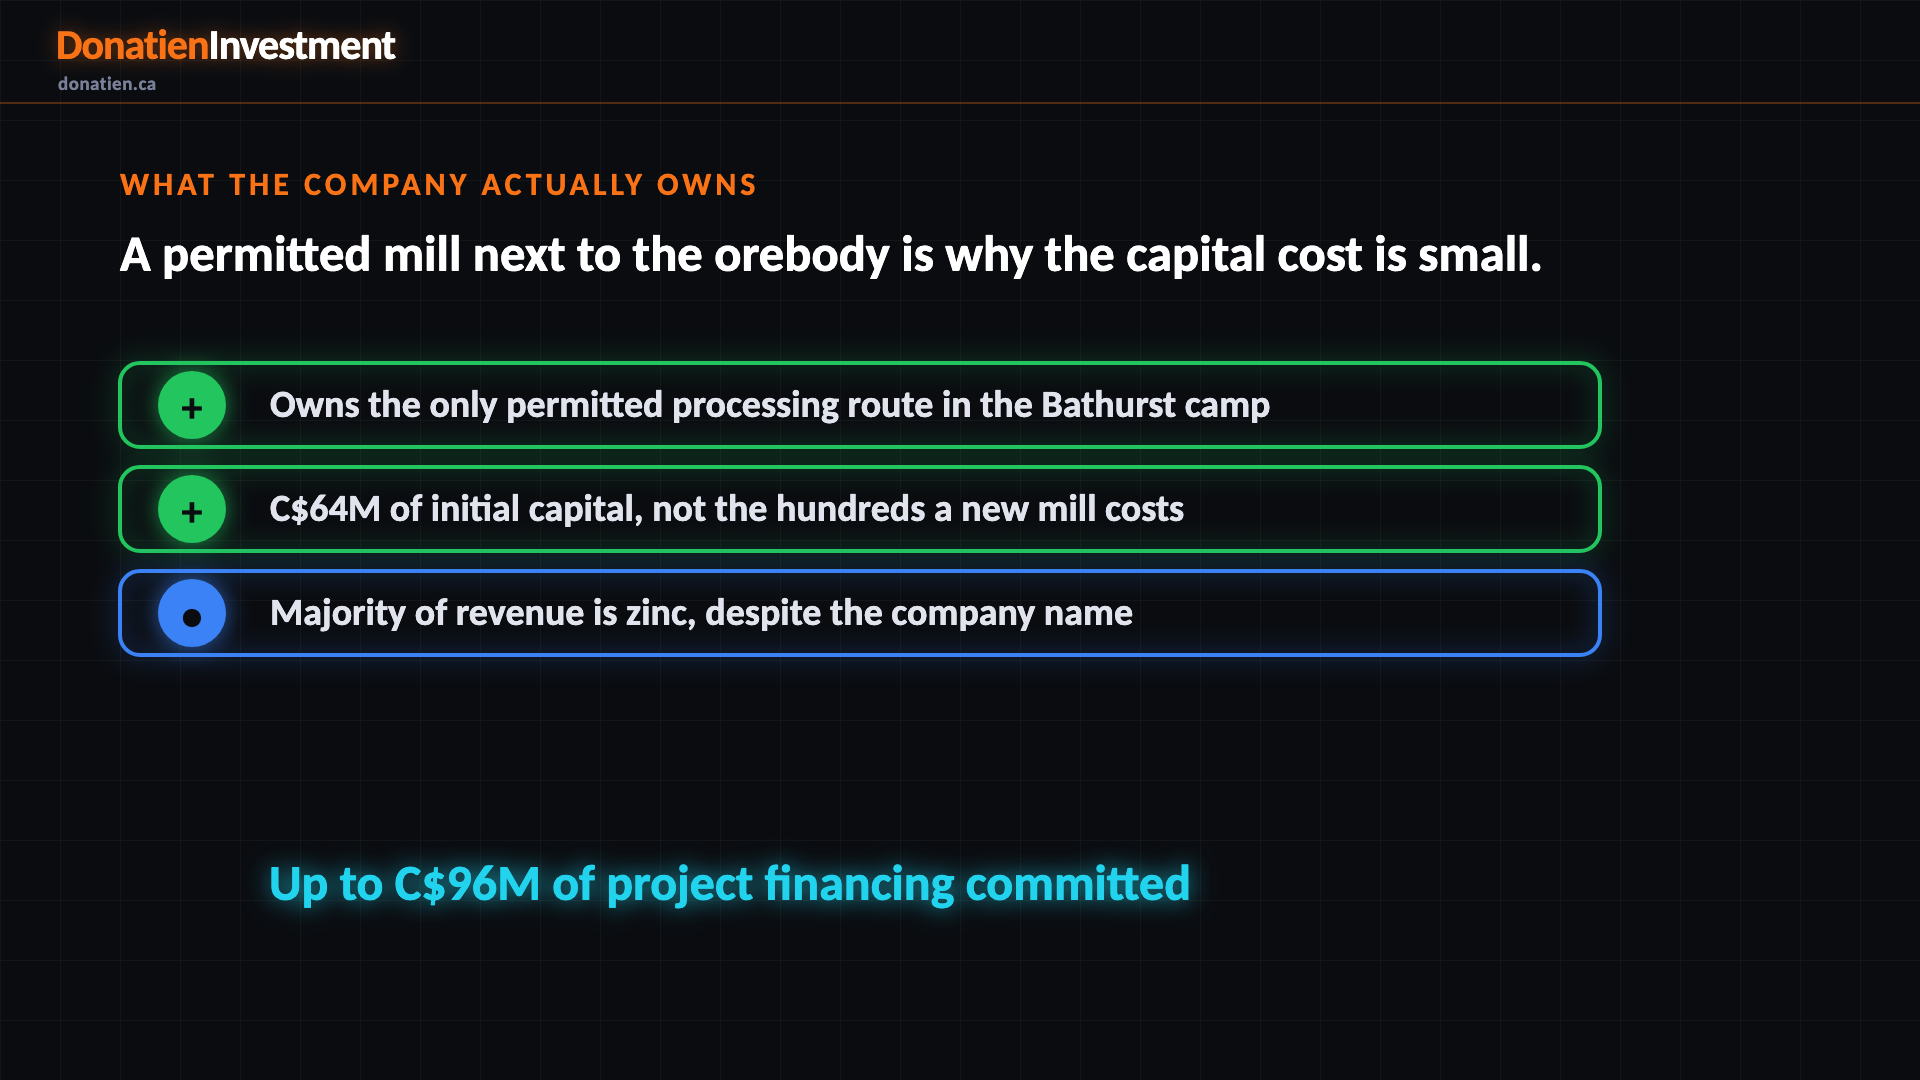
PEA: C$171M net present value, 36% return, 13.2-year life · Up to C$96M of project financing committed
The price against the asset
Value here is price against net asset value, built from the study and held at the study's own metal prices. That gives seventy-eight point five cents a share. Against a seventy cent price the shares trade at one point three seven times what the framework says is warranted, which is the full band - so no strong buy, and no amplification. The margin is the uncomfortable part: three point eight million dollars of value separates this from a hard cap on every horizon, and a single input can close that on its own. Against it, the metal basket currently sits at one point five seven times the prices the valuation assumes, and none of that upside is counted.
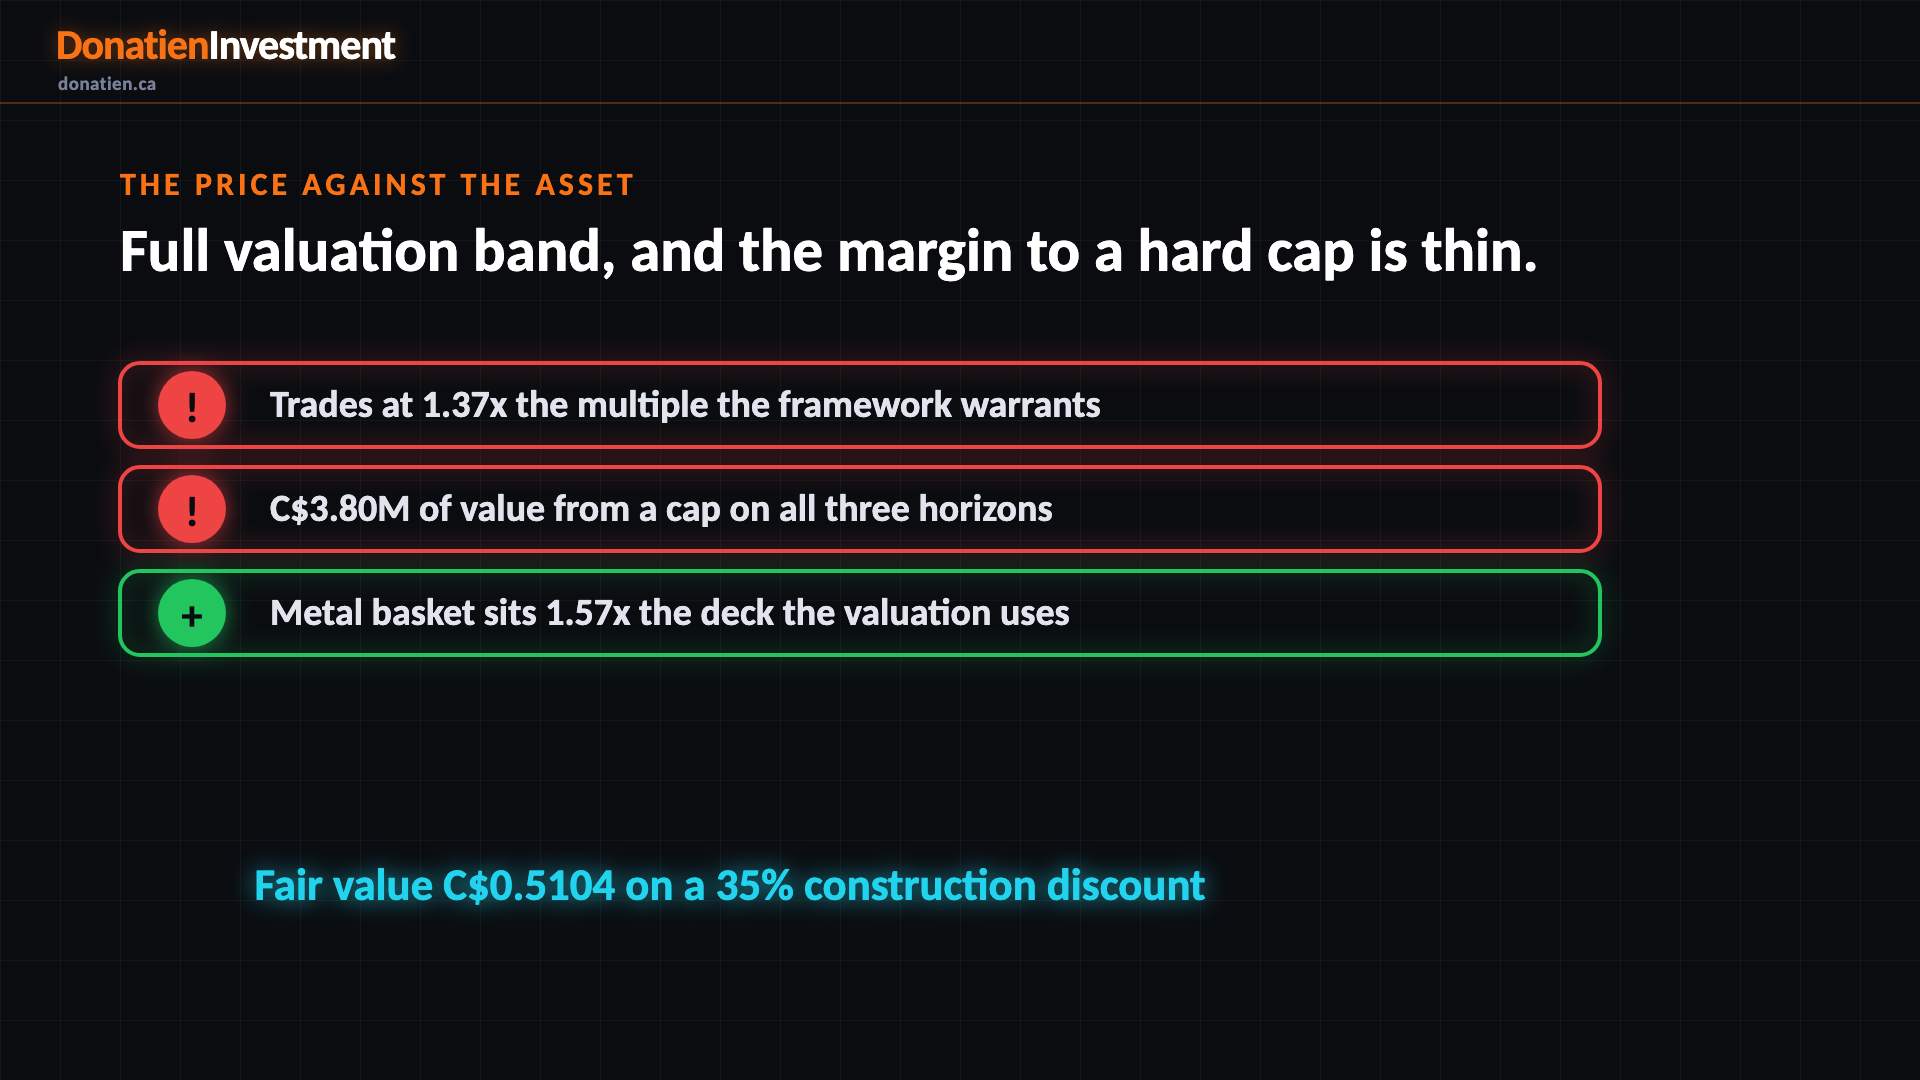
Net asset value C$0.7853 a share against a C$0.70 price · Fair value C$0.5104 on a 35% construction discount
What could go wrong
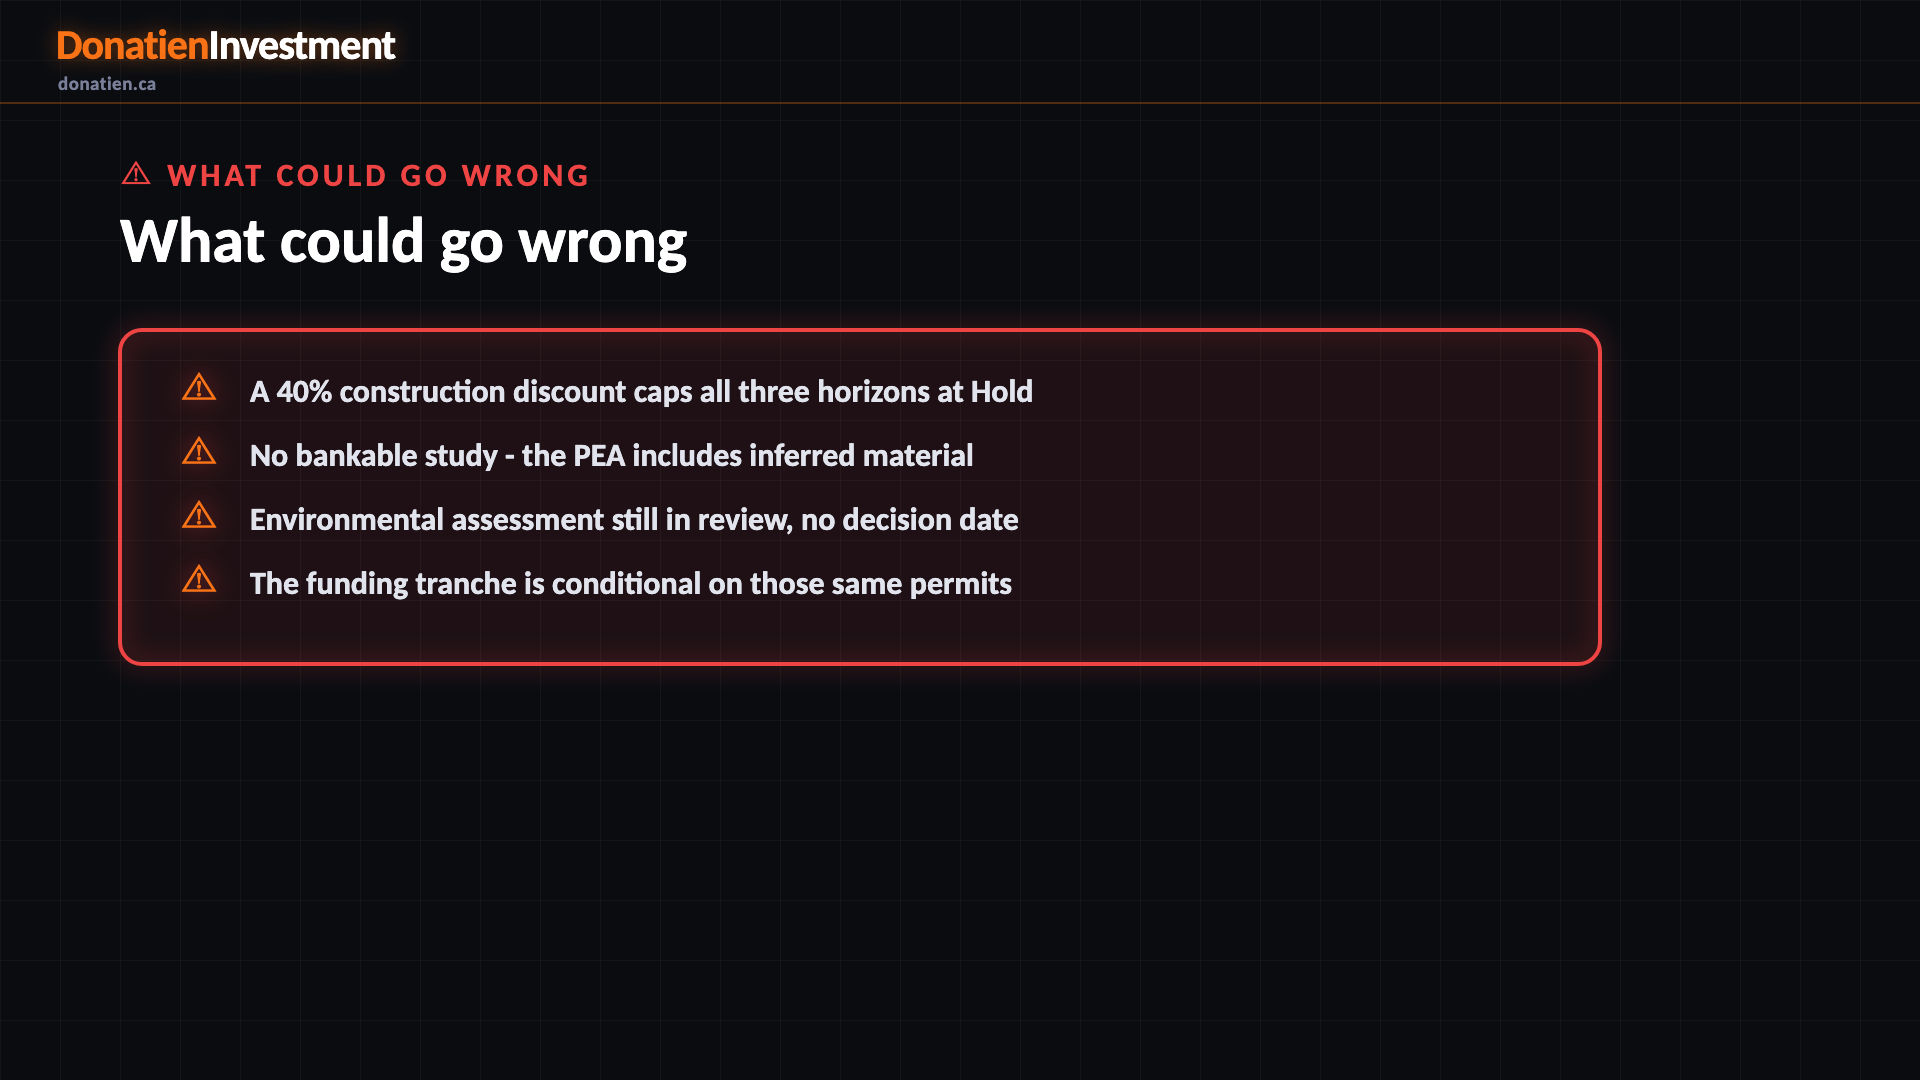
The valuation band is not robust, and it is one-sided in the wrong direction. The framework discounts a pre-production project by thirty to fifty per cent for construction risk; this report uses thirty-five, and at the midpoint of forty the signal would cap at hold on every horizon. There is no bankable study - the feasibility study is due in December and may revise the capital cost. The environmental assessment is still in review with no decision date, and the largest tranche of the financing is conditional on those very permits, so committed is not the same as drawn. The warrants at twenty-five cents dilute the count by eleven per cent before the middle of November. And this is one asset, pre-revenue, on a venture listing trading about a hundred and twenty-four thousand dollars a day - liquidity, not conviction, is what limits position size.
Risk vs Reward
Bull one dollar ten at twenty-two per cent, fifty-seven per cent above the price, and it needs two things: the construction discount to unwind as the study and the permit land, and the market to begin pricing some of the gap between the study's metal prices and today's. Base seventy-nine cents at fifty-five per cent, about thirteen per cent up, which is roughly the asset value with the discount gone and nothing assumed about metal prices. Bear forty-five cents at twenty-three per cent, thirty-six per cent down, on the feasibility study revising the capital cost up by thirty per cent. The probability-weighted value is seventy-eight cents. Note that the bear is weighted only one point below the bull - the December study is a two-sided event.
The verdict
Hold on the short horizon, buy on the medium and long, and the conviction ladder reads wait because no entry path is open. No exit rule is live: the stop at sixty-two and a half cents sits almost eleven per cent below, and every thesis condition reads clear. It stays a Donatien Pick because the automatic stop needs no buy on any horizon, and two of three are buys. Be plain about what this is: a pre-revenue single-asset developer on a venture exchange, priced above the asset value the study supports, whose valuation band a single assumption would break. The report carries three open findings from its own audit, published rather than smoothed, and the biggest of them is that the base and bull targets both imply a valuation this framework's own gate would cap at hold.
This report is refreshed on the thirtieth of September, when the July-quarter accounts are due. It is a quantitative framework for educational purposes only, and it is not financial advice. Always do your own research.
Read the full report on donatien.ca →